Debt methods - Avalanche vs. Snowball: Which One Actually Saves More Money?
The Great Debate in Debt Payoff
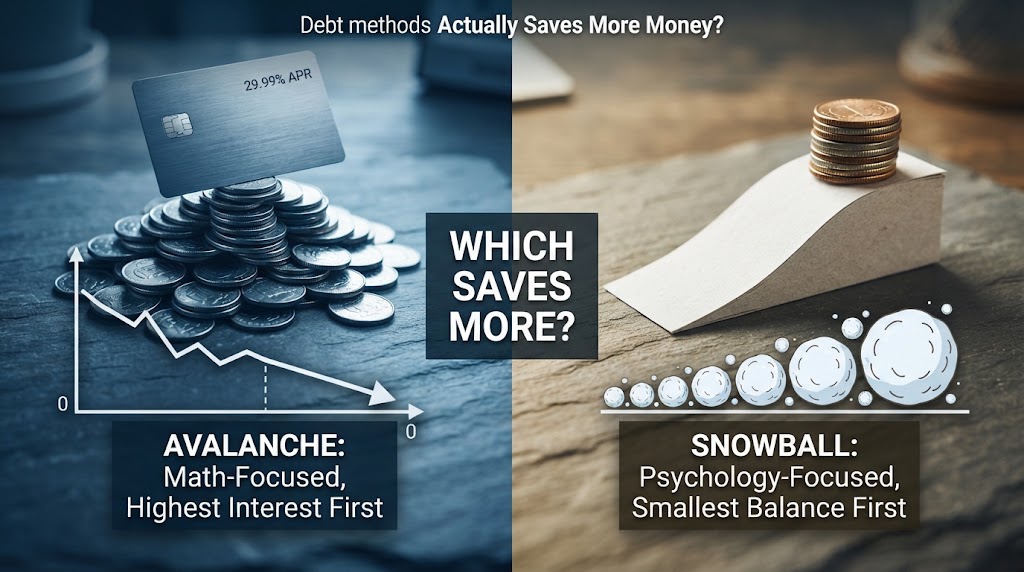
When you finally decide to tackle your credit card debt head-on, you hit your first strategic decision: which account do you pay off first? The two most popular schools of thought are the Debt Avalanche and the Debt Snowball. While both work, they approach your balances from completely opposite directions.- The Debt Avalanche (Maximum Math Efficiency)
The debt avalanche strategy focuses purely on interest rates. - How it works: You list your debts in order from the highest APR to the lowest APR. You pay the absolute minimum on everything, and every extra dollar goes toward the card with the highest interest rate.
- The Benefit: Mathematically, this is the optimal path. It minimizes the total amount of interest you will ever pay to the bank and gets you out of debt the fastest.
- The Debt Snowball (Psychological Momentum)
The debt snowball strategy, popularized by Dave Ramsey, focuses purely on balance sizes. - How it works: You list your debts from the smallest balance to the largest balance, regardless of interest rate. You throw all extra cash at the smallest balance until it is completely gone, then roll that payment into the next smallest.
- The Benefit: Quick wins. Knocking out a small $500 card in month one gives you an immediate psychological boost and keeps you motivated.
If you are disciplined and want to save every possible dollar in interest, go with the Avalanche. If you struggle with motivation and need quick victories to stay on track, go with the Snowball. No matter which method you choose, you can use Cut The Card (https://www.cutthecard.net) to model both strategies side-by-side and see your exact debt-free date.