

The 80/20 Debt Acceleration Rule: How to Allocate Side Hustle Income Without Burning Out
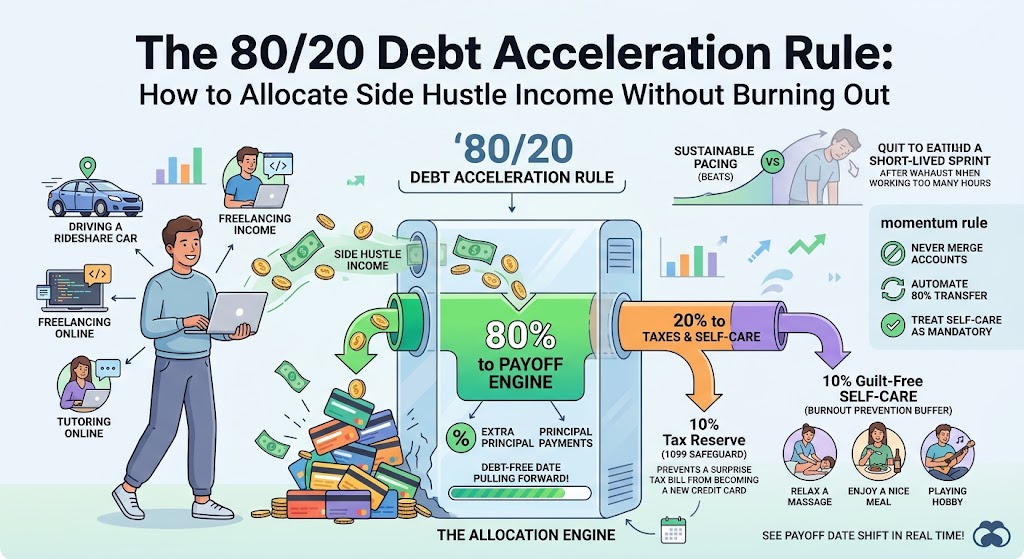
Picking up extra income—whether driving rideshare, freelancing, tutoring, or selling products—is one of the most powerful accelerators on any debt payoff journey.
When you dedicate extra income directly to credit card balances, you aren't limited by your fixed salary. Every extra $100 earned can be thrown straight at high APR interest.
However, side hustles come with a notorious trap: Side Hustle Burnout. People start by working 15 extra hours a week and throwing 100% of their earnings at debt. After two months of exhausting work with zero reward or fun, frustration sets in, they quit the side hustle, and spending leaks return.
To make side-income debt payoff work long term, you need a sustainable allocation system: The 80/20 Debt Acceleration Rule.
How the 80/20 Rule Works
Every time a side hustle payout or freelance payment hits your checking account, split the net cash into two distinct buckets before spending a single cent:
Bucket 1: 80% to the Payoff Engine
Eighty percent of your side hustle income goes directly toward your targeted credit card balance (following your Debt Avalanche or Debt Snowball priority order).
The Power of Extra Payments: Because your baseline monthly job salary already covers your fixed living expenses and minimum card payments, 100% of this 80% allocation attacks raw principal, shaving off compound interest at maximum speed.
Bucket 2: 20% for Taxes & Sustainable Self-Care
The remaining 20% is split equally between two essential safeguards:
10% Reserved for Taxes (1099 Side Income): Unlike W-2 employment, freelance and gig income doesn't withhold taxes automatically. Reserving cash prevents a surprising April tax bill from becoming a new credit card emergency.
10% Reserved for Guilt-Free Self-Care: This is your 'burnout prevention buffer.' Whether it's a nice meal out, a massage, or funding a hobby, this reward creates a direct psychological link between working extra hours and enjoying tangible life benefits today.
A Real-World Example: $500 Freelance Payout
Suppose you complete a freelance project or weekend gig and receive a $500 payout:
$400 (80%): Transferred immediately as an extra principal payment to your highest-APR credit card.
$50 (10%): Transferred to a high-yield savings sub-account labeled 'Tax Reserve.'
$50 (10%): Left in your spending account for guilt-free personal enjoyment.
You've made a massive $400 dent in your credit card debt, protected yourself from tax season shock, and rewarded yourself for your hard work—keeping your motivation high for next week.
3 Rules to Keep Side-Hustle Momentum Going
1. Never Merge Side Income with Regular Checking: Keep gig income separate until you perform the 80/20 split so extra earnings don't dissolve into groceries or utility bills.
2. Automate the 80% Transfer Instantly: The moment side money clears, execute the 80% payment immediately. Don't leave cash sitting in checking for days where impulse spending can creep in.
3. Treat the 10% Self-Care as Mandatory: Do not skip the self-care reward out of guilt. Sustainable pacing beats short-lived sprints every single time.
See Your Payoff Date Shift in Real Time
Even an extra $100 or $200 a month from a side hustle can pull your debt-free date forward by years.
👉 Plug Variable Extra Payments into Cut The Card – Use our dynamic payoff engine to see exactly how much time and interest money your 80% side-hustle contributions shave off your timeline!
Enjoyed this post? Never miss an update!
