The $50 Acceleration Method: How Micro-Payments Slash Years Off Credit Card Debt
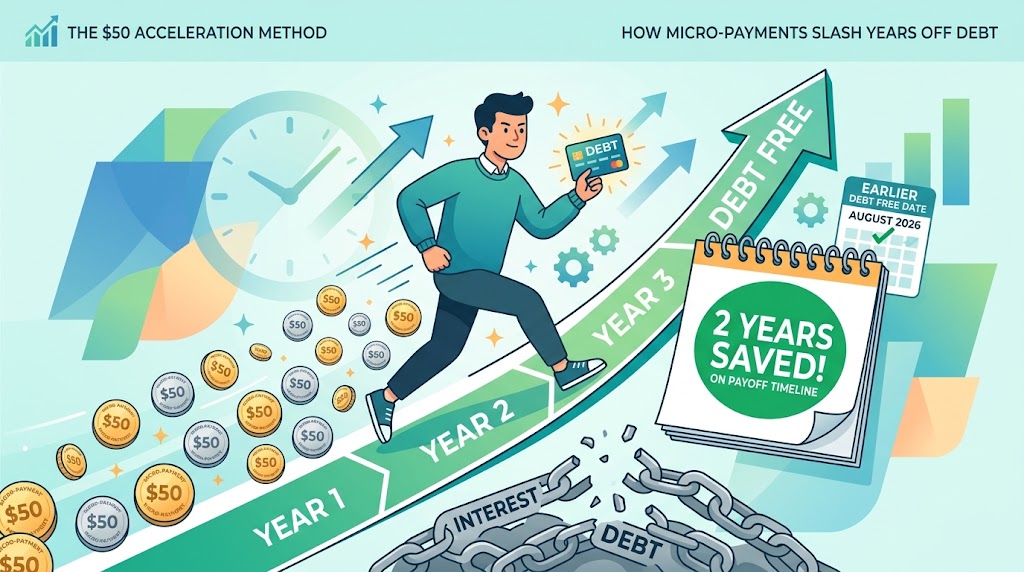
One of the most common excuses people make when dealing with heavy credit card debt is: "I only have $30 or $50 extra a month, so why bother? It's not going to make a difference on a $10,000 balance."
This mindset is understandable, but mathematically incorrect.
Because credit card interest compounds daily, even small extra payments make a dramatic, non-linear impact on your debt timeline.
The Power of Micro-Payments: A Real-World Comparison
Let's look at what happens when you add just $50 per month to a typical credit card balance.
- Credit Card Balance: $8,000
- Interest Rate (APR): 24%
- Standard Minimum Payment: ~$200/month
- Minimum Payments Only ($200/mo): ~70 Months (5.8 Years) | Total Interest: $6,840
- Minimum Payment + $50/Month ($250/mo): ~46 Months (3.8 Years) | Total Interest: $4,080
- Total Difference: 24 Months Saved & $2,760 Saved in Interest!
An extra $50 per month—roughly $1.64 per day—knocks two full years off your debt journey and keeps $2,760 in your pocket instead of giving it to the bank.
Why Micro-Payments Work So Well
- Compounding Works in Reverse: Credit card interest calculates daily based on your average daily balance. Sending small amounts early reduces the daily principal upon which tomorrow's interest charge is calculated.
- Low Psychological Resistance: Finding $500 extra a month requires major budget overhauls. Finding $50 requires small, painless tweaks—like skipping two takeout meals or cancelling an unneeded subscription.
- Builds Financial Consistency: Action creates motivation. Sending small micro-payments throughout the month keeps your debt payoff goal top-of-mind.
Where to Find Your First Extra $50 This Week
The 48-Hour Cart Freeze: Wait two days before checking out online purchases; impulse items often drop off.
Negotiate One Utility/Bill: Call your internet or mobile provider and ask for current promotional pricing.
Audit Subscriptions: Cancel one unused streaming service or membership today.
See What Your Extra $50 Can Do
Want to see the exact month and year you will be debt-free if you add $25, $50, or $100 to your monthly payments?
Cut The Card calculates your custom payoff schedule instantly. Experiment with different payment amounts and watch your payoff date jump forward!
👉 Calculate your custom debt payoff schedule on Cut The Card for free!
Enjoyed this post? Never miss an update!
