How to Negotiate a Lower Credit Card APR with Your Card Issuer (With Scripts)
Most people assume credit card interest rates are set in stone. If your statement says 24.99% APR, you pay 24.99% APR. The truth? Credit card APRs are negotiable.
Credit card issuers operate in a hyper-competitive market. Retaining an existing customer who makes on-time payments is far cheaper for a bank than acquiring a new customer or risking a default. If you have a history of on-time payments, a quick phone call to customer service can drop your interest rate by 3% to 7%—or land you a temporary hardship rate as low as 0% to 9%.
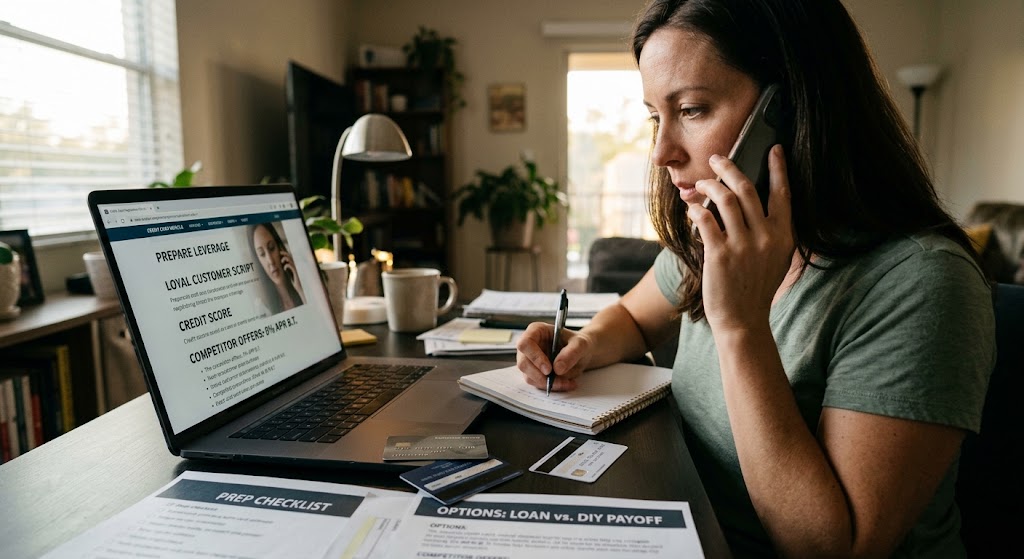
Here is the exact step-by-step strategy to prepare for the call, along with word-for-word scripts you can read directly off your screen.
What to Prepare Before You Call
Before dialing the customer service number on the back of your card, gather your leverage:
1. Check Your On-Time Payment Record: Know how long you’ve been a customer and confirm you haven't missed a payment in the last 12+ months.
2. Know Your Current Credit Score: A score that has improved since you opened the account is strong leverage.
3. Research Competitor Offers: Find 1 or 2 balance transfer card offers currently available online (e.g., a competitor offering 0% APR for 18 months or a fixed card with a 15% APR).
Option A: The 'Loyal Customer' Script (For Good Standing)
Use this script if you have made consistent on-time payments and have decent credit:
| "Hi,
I’ve been a loyal customer with [Bank Name] for [X] years, and
I’ve maintained a clean on-time payment record. I’m currently reviewing my accounts and noticed my interest rate is [Your Current APR, e.g., 24.99%]. I recently received an offer from another card issuer for a balance transfer with 0% APR for 18 months and a permanent rate of 15%. I’d prefer to keep my business with [Bank Name] —what can you do to lower my APR today?" |
If they say no or offer a small drop (e.g., 1%):
"I
appreciate that, but a 1% reduction still leaves me well above
market offers. Is there a supervisor or retention department
representative |
Option B: The 'Temporary Hardship / Rate Reduction' Script
Use this script if you are experiencing cash-flow strain, job transition, or high medical costs, and need a temporary reduction to keep up with payments:
"Hi,
I am reaching out because I am committed to paying off my balance
with [Bank Name], but my current APR of [X%] is making it
difficult |
Card issuers often have internal hardship programs that reduce APRs to single digits (or 0%) for 6 to 12 months, provided you agree to refrain from making new purchases on the card while enrolled.
What to Do If They Say No
If the customer service representative tells you there are no available offers or reductions, don't sweat it.
1. Thank Them and Call Back Later: Reps have different levels of training, authorization, and promotional tools available on any given day. Calling back 48 hours later can yield a completely different outcome with a different agent.
2. Ask When Promotions Refresh: Ask: "When do internal promotional offers update on my account?" (Many banks refresh promotional eligibility on the 1st of the month or quarterly).
3. Execute Plan B: If your bank refuses to lower your rate, pivot to a 0% balance transfer card or apply the Debt Avalanche Method to crush that high-APR card first.
Recalculate Your Payoff Date Immediately
Did you manage to get your APR knocked down from 24% to 18%? That small change can slice months—or years—off your debt payoff journey.
👉 Log Your New APR into Your Cut The Card Dashboard – Update your account interest rates in real-time to see your revised payoff timeline and discover how much interest money stays in your pocket!
Enjoyed this post? Never miss an update!