The 'Post-Payoff' Maintenance Plan: What to Do the Month After You Reach $0 Balance
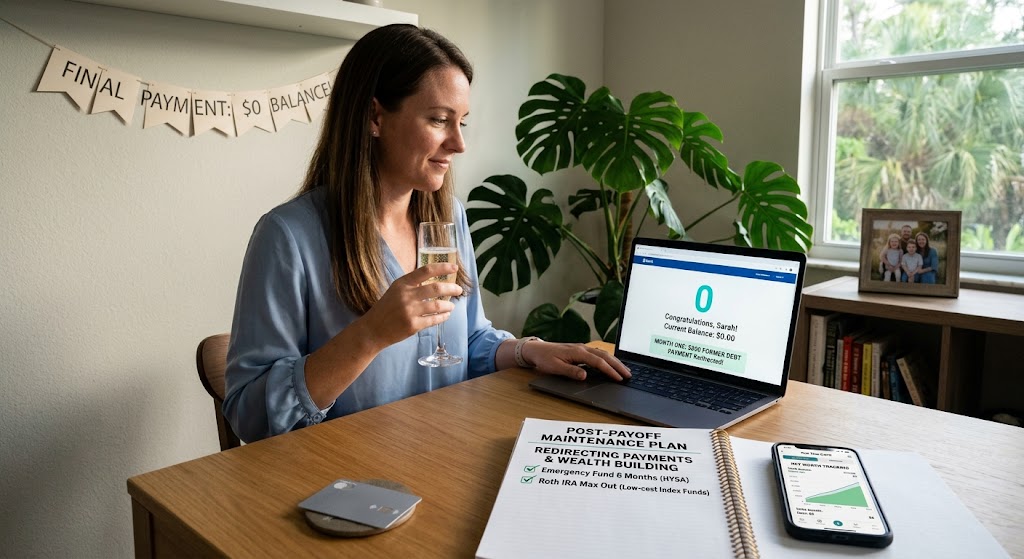
You logged into your account, submitted your final payment, and watched your credit card balance hit **$0.00**.
Crossing the debt-free finish line is a life-changing milestone. But reaching $0 balance is only half the battle—staying at $0 balance for the rest of your life is the true objective.
The first 30 to 90 days after becoming debt-free represent a critical transition period. Without a clear plan for your freed-up cash flow, lifestyle creep can quietly set in, setting the stage for future debt relapse. Here is your complete Post-Payoff Maintenance Plan.
1. What to Do with Your Paid-Off Credit Cards
Should you close your paid-off credit card accounts or keep them open?
Keep Open IF: The card has no annual fee and represents one of your oldest credit accounts. Keeping it open maintains your credit history length and lowers your overall credit utilization ratio, protecting your credit score. Put a small recurring utility bill on auto-pay and set up full auto-pay to keep it active.
Close IF: The card carries a high annual fee, or if keeping the account open presents an ongoing psychological temptation to spend beyond your means. Peace of mind always trumps a minor temporary credit score dip.
2. Redirect Former Debt Payments into Wealth Building
If you were paying $800 a month toward credit card debt, hitting $0 balance means you just gave yourself an $800 monthly raise.
Do not let this cash dissolve into daily spending. Immediately automate your former debt payment into building long-term wealth:
Full Emergency Fund (3–6 Months): Expand your $1,000 starter buffer into a robust 3 to 6-month liquid emergency fund in a High-Yield Savings Account.
Retirement & Investment Accounts: Max out employer 401(k) matches, fund a Roth IRA, or invest in low-cost index funds.
Sinking Funds for Major Goals: Establish dedicated savings buckets for home maintenance, auto upgrades, travel, or family goals.
3. Establish Credit Utilization Guardrails
To use credit cards safely as a tool for points, security, and cash back without ever carrying a balance again, follow the **20% Utilization Rule**:
Never charge more than 20% of your available credit limit in a given cycle, and set up automatic statement balance payments every single month so you never pay another dime in interest.
Transition Cut The Card into Net Worth Mode
Your journey doesn't end at $0 debt—it shifts toward building net worth.
👉 Transition Your Cut The Card Dashboard – Switch your profile view from debt reduction to asset tracking and watch your net worth grow month after month!
Enjoyed this post? Never miss an update!
