

Triage Finance: Escaping High-APR Title Loans Before You Lose Your Vehicle
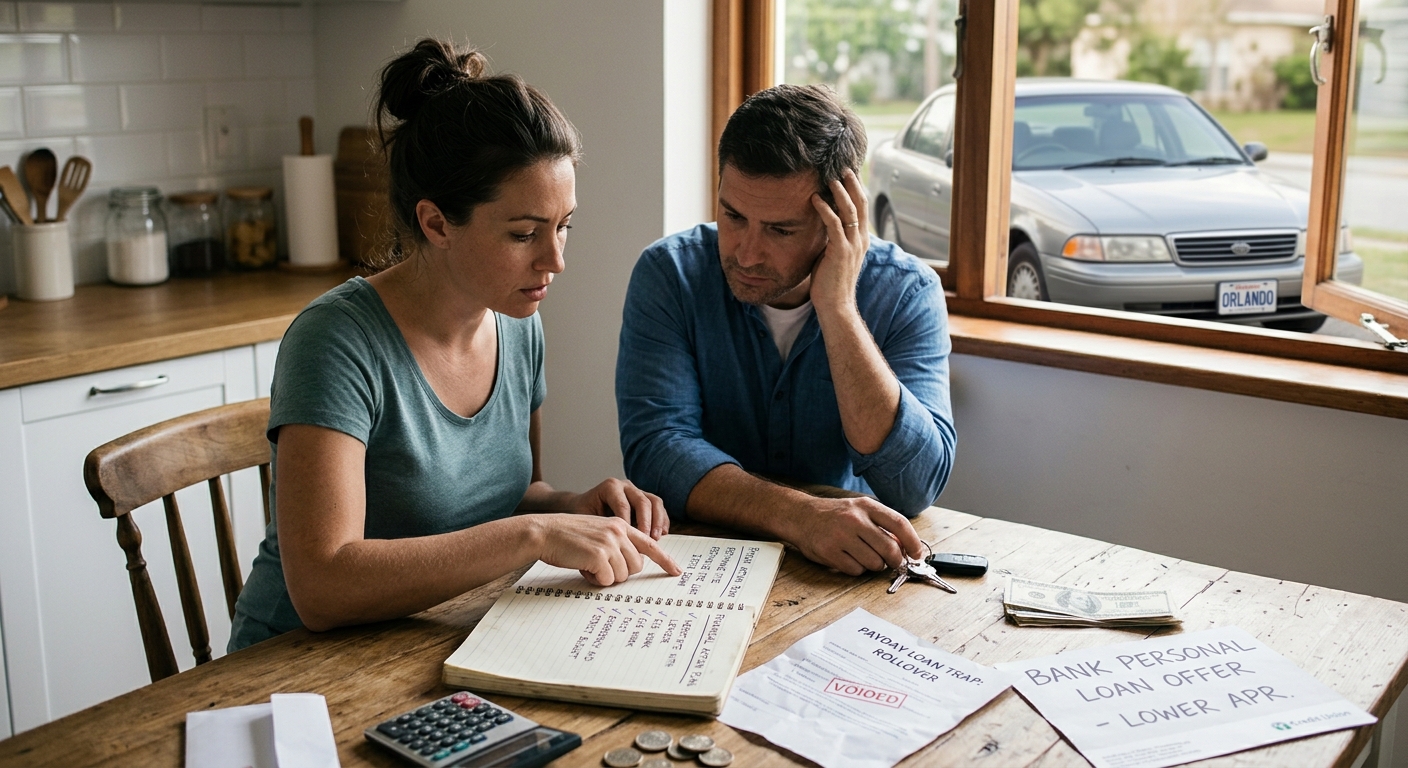
For many households, a vehicle is not a luxury; it is a lifeline. It connects people to their jobs, their children's schools, medical appointments, and essential community services. When an unexpected financial shortfall occurs—perhaps during the back-to-school season or the expensive holiday months—a title loan can seem like a convenient way to get through a difficult week.
But that short-term solution can become a much larger financial problem. A title loan uses your vehicle as collateral, meaning the lender may have the right to repossess it if you default, subject to the terms of the agreement and applicable law. High annual percentage rates (APRs), fees, and short repayment periods can make these loans particularly difficult to repay.
The possibility of losing your vehicle can create enormous stress. Without reliable transportation, getting to work, caring for family, and handling everyday responsibilities may become even harder. Getting out of a title loan requires a clear plan that addresses the immediate risk while working toward a more affordable way to repay the debt.
Navigating the Exit Strategy
A practical approach has two priorities: understand how to protect your vehicle from repossession and identify the most affordable realistic path to paying off the loan. The right steps will depend on your agreement, financial circumstances, and the laws where you live.
Prioritize Reducing the Principal
Start by finding out exactly how much you owe. Ask the lender for an itemized payoff amount that includes the outstanding principal, interest, fees, and any other charges. Review the agreement to understand when payments are due, what happens after a missed payment, and whether additional payments can be applied directly to the principal without a penalty.
Making only the minimum payment or repeatedly extending a loan may leave the principal largely unchanged while additional interest and fees accumulate. If your budget allows, direct extra money toward reducing the principal. Income from temporary work, a tax refund, or reduced discretionary spending may help. Before making a payment, confirm how the lender will apply it.
Explore Safer Refinancing Options
Replacing a high-cost title loan with a more affordable loan may be worth investigating. Depending on your credit, income, and available options, a bank or credit union may offer a personal loan with a lower APR and a more manageable repayment schedule.
Compare the full cost of each option—not just the monthly payment. Consider the APR, origination fees, repayment term, and total amount you will pay. A longer term can reduce monthly payments while increasing the total interest paid. Avoid taking on another loan unless the terms genuinely improve your situation and you can afford the payments.
Review Your Budget and Available Assets
If your regular income cannot cover the loan comfortably, look for realistic ways to create additional room in your budget. Temporarily reducing non-essential expenses, selling items you no longer need, or taking on occasional additional work may help you make a meaningful payment toward the balance.
Be careful not to sell something essential to your household or take on additional debt that creates a new financial problem. The goal is to improve your ability to repay the loan without sacrificing necessities.
Contact the Lender Before Missing a Payment
If you are struggling, contact the lender as early as possible. Explain what you can realistically afford and ask whether a modified payment schedule, hardship arrangement, or other alternative is available. Request any proposed agreement in writing before relying on it.
A lender is not required to offer a hardship arrangement, and a conversation does not automatically stop repossession. If you receive a default notice or believe repossession may be imminent, review your rights under local law and consider contacting a qualified consumer-law professional or legal aid organization.
Summary
Protecting your vehicle is about more than resolving a debt. It is about preserving the transportation you may depend on for work, family, and everyday life. Although high-interest title loans can be difficult to escape, taking informed steps early can give you more options.
Start by understanding the exact payoff amount and the terms of your agreement. Then compare realistic repayment and refinancing possibilities, review your budget, and communicate with the lender before the situation becomes more difficult. Once the immediate challenge is addressed, you can focus on building greater financial stability.
Disclaimer: This article is for educational purposes only and does not constitute professional financial, legal, or tax advice. Loan terms and consumer protections vary by location. Consult a qualified professional about your specific circumstances.
If credit-card debt is also part of your financial picture, CutTheCard can help you understand your balances and compare potential payoff strategies. Explore the tools at CutTheCard to see how different repayment approaches may affect your timeline and interest costs.
Enjoyed this post? Never miss an update!
